If you searched roarleveraging, you probably ran into a few websites using the name and wanted to know what it means. The answer is a little messy, because the term shows up in several different ways. This guide separates what’s verifiable from what’s marketing, then covers the financial and business ideas underneath, which are the useful part.
What Is RoarLeveraging?
RoarLeveraging is a brand name used by a cluster of blog-style websites covering finance, business growth, and marketing. It is not a regulated financial product, a licensed brokerage, or an established industry framework like Six Sigma or SWOT.
Here is what turns up when you look:
- One site describes itself as a hub for learning and growth that offers strategic insights and actionable guidance for individuals, businesses, and communities.
- Another domain presents it as a finance brand with a Dallas, Texas address.
- Several articles define “roar leveraging” in business terms: amplifying existing assets, relationships, and systems to get outsized results without a proportional increase in effort or cost.
- A financial-advisor article on one of these sites calls it “Relationship Oriented Automated Reach Leveraging”.
These descriptions don’t agree with each other. One treats it as a finance topic, another as a client-growth method, another as a general business mindset. That inconsistency tells you something about how to read the content.
Bottom line: treat “roarleveraging” as a label for a style of content about leverage, not as a proprietary system you need to buy into.
Why the Meaning Varies So Much
When several sites publish under one name with different definitions, the term is working more as an SEO keyword than as a defined methodology. The acronym expansions, founder claims, and “infoguide” titles vary from page to page.
That doesn’t make every article worthless. The underlying ideas (financial leverage, operational leverage, marketing ROI) are real and well documented. The branding is what’s loose.
Quick credibility check before you act on any “roarleveraging” advice:
- [ ] Is there a named, verifiable author with credentials (CFP, CFA, CPA, licensed attorney)?
- [ ] Does the site disclose how it makes money (ads, affiliate links, consulting)?
- [ ] Are there risk disclosures on anything involving borrowed money?
- [ ] Can you confirm the business address or registration independently?
- [ ] Do the numbers in the examples match what’s realistic?
If you can’t tick most of those boxes, use the content for vocabulary and ideas only, and verify the rest elsewhere.
The Core Idea: What “Leveraging” Actually Means
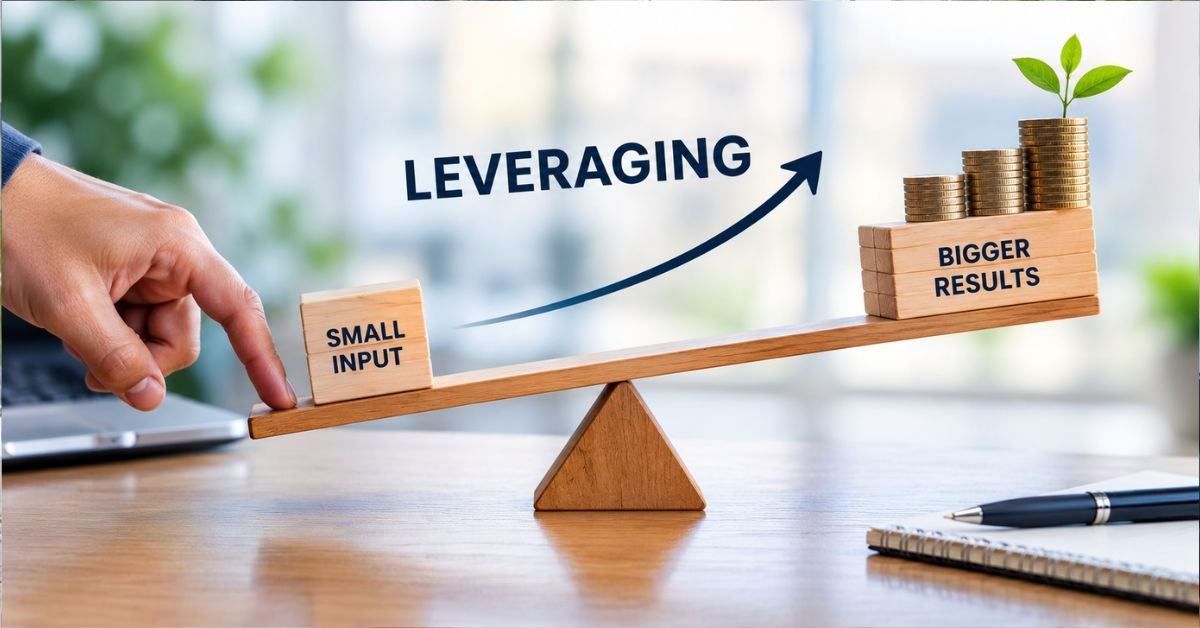
Strip the branding away and the concept is straightforward. Leverage means using a smaller input to control a larger result. In finance, it’s any technique involving borrowed funds to buy an investment.
The name comes from the physical lever. A small force goes in, a bigger force comes out. Money works the same way, in both directions.
A Simple Numerical Example
Say you have $10,000 and you buy $100,000 of an asset with 10:1 leverage. If the asset rises 10%, you gain $10,000, a 100% return on your own cash. If it drops 10%, you’ve lost everything you put in. A basic leverage explainer walks through this same 10:1 scenario.
That symmetry is the whole story. Leverage multiplies outcomes, not skill. A good decision becomes a great one, and a bad decision becomes a disaster.
The Three Types of Leverage People Mix Up
| Type | What It Means | Common Example | Main Risk |
| Financial leverage | Borrowing to fund an investment or purchase | Mortgage on a rental property, margin trading | Debt must be repaid even if the asset falls |
| Operating leverage | High fixed costs, low variable costs | Software company, factory with expensive equipment | Profits fall hard when revenue dips |
| Marketing/relationship leverage | Using audience, content, or referrals to scale reach | Email list, partnerships, systems that run without you | Results are slow and hard to measure precisely |
Most “roarleveraging” content blurs these three together. Keeping them separate makes your decisions much clearer.
How Financial Leverage Works in Practice
Where People Actually Use It
Most Americans already use leverage without calling it that:
- Home mortgages. A 20% down payment controls 100% of the asset.
- Business loans. Borrowing to buy equipment or inventory with an expected return above the interest cost.
- Margin accounts. Borrowing from a brokerage to buy more securities.
- Real estate investing. Financing rental properties so rent helps pay down the loan.
- Business owners. Equity holders leverage their investment by having the business borrow part of its financing.
Key Terms You Need to Know
- Margin: collateral your broker requires to cover possible losses.
- Leverage ratio: borrowed funds relative to your own capital.
- Margin call: a demand for more money when your position falls below a set level. The same explainer defines it as a broker demand for additional funds or collateral when a leveraged position’s value drops.
- Debt-to-equity ratio: how much of a business is funded by debt versus owner money. A firm that is called “highly leveraged” carries more debt than equity and operating cash.
Pros and Cons
| Pros | Cons |
| Amplifies returns on a small amount of capital | Amplifies losses just as strongly |
| Lets you buy assets you couldn’t afford outright | Interest costs eat into returns |
| Can improve return on equity for businesses | Lenders can force you to sell at a bad moment |
| Interest may be tax-deductible in some situations | Missing payments can damage credit or lead to default |
One veteran investment executive put the biggest danger plainly: leverage magnifies losses, and a lender may close out your position at a loss at a time you don’t choose. That forced-sale risk is what separates a bad year from a wiped-out account.
The Business Version: Leveraging Assets Instead of Debt
Some “roarleveraging” pages use the word in a business-growth sense. Here, leverage means getting more output from what you already have: audience, systems, relationships, and content.
This version is real and useful. Examples:
- Service providers: turning a repeat process into a template, course, or productized service.
- Product businesses: negotiating better supplier terms or raising customer lifetime value.
- Digital businesses: publishing content once that keeps bringing in leads.
One marketing-focused article on these sites frames ad spend as an investment: if $5,000 in ads brings 50 customers worth $500 each over their lifetime, the spend turned into $25,000, a 5x return. The framing is sound, with one caveat. Lifetime value is an estimate. Treat it as a hypothesis until real customer data confirms it.
A Practical Way to Apply Marketing Leverage
- Calculate your real customer acquisition cost. Include ad spend, tools, and your time.
- Estimate customer lifetime value conservatively. Use actual repeat purchase data, not hopes.
- Set a payback target. Decide how many months you can wait to recover the spend.
- Test small first. Spend a fraction of the budget and measure.
- Scale only what is proven. Increase spend on channels where the numbers hold up.
Risks and Red Flags to Watch For
Because the term is used loosely online, some caution is warranted.
Be skeptical when you see:
- Promises of guaranteed returns or “predictable” profit from borrowed money.
- Payback timelines stated as fact with no source or sample size.
- Pressure to act quickly or contact a specific person.
- Acronym definitions that change from article to article.
- Heavy keyword repetition in place of real explanation.
What to do instead:
- Check any broker or advisor in the SEC’s Investment Adviser Public Disclosure database and FINRA BrokerCheck.
- Confirm any lender is licensed in your state.
- Read the full margin or loan agreement, especially the section on forced liquidation.
- Stress-test your plan: if the asset drops 30%, can you still make every payment?
Educational blog content, including this guide, isn’t personalized advice. For decisions involving real money and debt, talk to a licensed financial professional.
Troubleshooting: Common Leverage Mistakes and Fixes
| Problem | Why It Happens | Fix |
| Losses larger than expected | Leverage ratio too high for the volatility | Lower the ratio; keep a cash buffer |
| Margin call hits during a dip | No reserve capital | Hold extra funds; avoid maxing out margin |
| Interest eats the gains | Borrowing cost exceeds asset return | Only borrow when expected return clearly beats the rate |
| Marketing “ROI” never materializes | Lifetime value was overestimated | Rebuild the forecast from real customer data |
| Cash flow tight despite “profit” | Debt payments due before returns arrive | Match loan terms to when income actually arrives |
A Safe Starting Checklist
- [ ] Define which kind of leverage you’re considering: financial, operating, or marketing.
- [ ] Write down the worst realistic outcome and confirm you can survive it.
- [ ] Compare the cost of borrowing with the realistic return.
- [ ] Keep an emergency fund separate from any leveraged position.
- [ ] Verify every advisor, broker, or lender through official US databases.
- [ ] Start small and increase only after results are measurable.
Is RoarLeveraging Worth Your Time?
As a brand, it’s one of several loosely defined content sites, so judge each page on its own evidence. As an idea, leverage is one of the most important concepts in finance and business, and understanding it properly protects you from the downside.
Use the term as a prompt to ask better questions: What am I amplifying? What happens if it goes wrong? Who verifies the claims?
Frequently Asked Questions
What does it mean to leverage people?
It means getting more done by using other people’s skills, time, networks, or knowledge, usually through delegation, teamwork, or partnerships. Done well, everyone benefits. Done badly, it’s just using people.
What does it mean to have leverage over someone?
It means holding something they want or need, so you can influence their decisions. A job offer, a signed contract, or inside information can all give you that power, and it works best when the other person has few alternatives.
What does leverage mean in real life?
It’s using a small advantage to produce a much bigger result. A mortgage lets a modest down payment control a whole house. A skill that’s in demand lets you negotiate a higher salary. A single piece of content can bring in customers for years.
What are three types of leverage?
- Financial leverage: using borrowed money to control a larger asset.
- Operating leverage: using fixed costs so extra sales raise profit faster than expenses.
- Personal or social leverage: using your skills, relationships, or reputation to gain influence.
What is a simple word for leverage?
Advantage is the closest everyday word. Depending on context, you can also say influence, pull, edge, or clout.
